Rolling coverage of the latest economic and financial news
Global financial system is failing developing countries, says Ed Miliband
6m agoEd Miliband: Global financial system is failing developing countries
20m agoNot building third runway would be 'huge missed opportunity', Heathrow boss claims
27m agoBoE's Pill wary of predictions of four rate rises
39m agoBank of England governor and IMF warn of rising cyber risks
48m agoIMF's Georgieva urges US to get its house in order
1h agoIntroduction: IMF sounds alarm over rising government borrowing costs
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
The jump in government borrowing costs this year is causing concerns at the International Monetary Fund, as policymakers gather in Bangkok for its annual meeting.
In its new fiscal monitor report, released this morning, the IMF is warning that the rise in sovereign bond yields has “raised the fiscal stakes” facing governments, as they try to keep borrowing under control.
Higher borrowing costs are adding to fiscal pressures at a time of high debt, making credible consolidation more urgent, it points out.
And it is demanding action, warning that “the more countries wait, the more painful the adjustment becomes.”
This is easier said than done, though! France, for example, faces a struggle to push through a budget that would only cut its annual deficit to 5% of GDP. And in the UK, chancellor John Healey could face a battle with his own MPs if he proposes welfare cuts in his budget later this month.
The IMF points out that since February – when the Iran war began, and oil prices jumped – the average 10-year government bond yield for G7 countries increased by over 1 percentage point, reaching its highest level in nearly two decades.
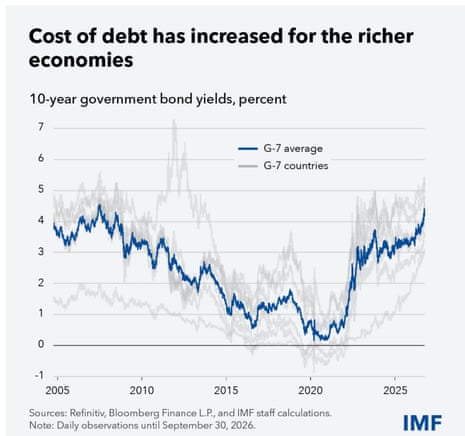
With global public debt expected to exceed 100 percent of global GDP for the first time since the immediate aftermath of World War II, this is not a great time for borrowing costs to be hitting the roof.
Or, as the IMF puts it:
In major advanced economies, high debt, spending pressures, and the prospect of large bond issuance in the years ahead are putting upward pressure on the yields investors demand to hold longer-term bonds. Higher benchmark yields in major economies can also spill across borders, worsening debt dynamics elsewhere.
In major advanced economies, high debt, spending pressures, and the prospect of large bond issuance in the years ahead are putting upward pressure on the yields investors demand to hold longer-term bonds.
Higher benchmark yields in major economies can also spill across borders, worsening debt dynamics elsewhere.
The IMF points out that the cost of servicing government debts have already jumped sharply. In the US, for example, interest payments are projected to climb from about 2.8% of GDP before the pandemic to 5.7% in 2031, which is roughly equal to projected expenditure on Social Security.
It’s worse for low-income countries, where interest payments today consume over 15% of tax revenues.
The agenda
9am BST: IEA oil market report
9am BST: Foreign secretary Ed Miliband speaks at the IMF Annual Meeting in Bangkok
9.15am: Treasury select committee hearing on Heathrow expansion plans
1.30pm US inflation report for September
2.15pm Treasury Committee hearing on the Budget 2026
Tim Jones, policy director at Debt Justice, has welcomed Ed Miliband’s call for a ‘new deal’ on debt for emerging economies:
“We welcome Ed Miliband’s commitment to action on debt during the UK G20 Presidency. He is right that the debt relief system urgently needs an overhaul. This must include deeper debt relief, a suspension of payments during negotiations and measures to ensure private lenders participate.” “Crucially, private lenders must share the cost of debt relief schemes. Otherwise public money will just bail out private lenders rather than be used for investment.”
“We welcome Ed Miliband’s commitment to action on debt during the UK G20 Presidency. He is right that the debt relief system urgently needs an overhaul. This must include deeper debt relief, a suspension of payments during negotiations and measures to ensure private lenders participate.”
“Crucially, private lenders must share the cost of debt relief schemes. Otherwise public money will just bail out private lenders rather than be used for investment.”
Ed Miliband is due to speak at the IMF meeting today, and our economics editor Heather Stewart has the inside line on his plans:
The foreign secretary, Ed Miliband, will claim the global financial system is failing developing countries, as he calls for a “new deal” for governments struggling under the burden of debt.
Promising to throw the UK’s diplomatic weight behind urgent reform, he will evoke the example of the Gleneagles summit under the last Labour government in 2005 – the culmination of the Make Poverty History campaign.
“The global financial system and indeed the global order is failing to serve developing countries on debt, on resilience and on climate. This is not just against our values but against our national interest,” Miliband is expected to say.
“In the interconnected world we live in, more than ever, the opportunities and challenges we confront are collective.”
Speaking in Bangkok on Wednesday, he will call for the World Bank and other multilateral development banks (MDBs) to use the resources they have available to lighten the load for governments trapped by hefty borrowing costs.
“We need action on developing country debt through the MDBs,” he is expected to say.
“Action that leverages the balance sheets of the international financial institutions to support these countries to repay over longer time horizons, and crucially, refinancing, with better rates, to give them precious fiscal space.”
Here’s the full story:
Away from the IMF meeting, the boss of Heathrow airport has claimed it would be a “huge missed opportunity” not to build a third runway.
Thomas Woldbye told BBC Radio 4’s Today programme it would be “good to know” the government’s position on the project, after prime minister Andy Burnham refused to say whether he backed expansion.
Woldbye, who is due to appear before parliament’s transport committee today to discuss the issue, warned that Heathrow’s shareholders will invest elsewhere in the world if the third runway is blocked, rather than in the UK, arguing:
“It’s not about allocating this money elsewhere. It’s private money. It’s not public money. So hence, it will not go into the UK. I think that would be really a sad, huge missed opportunity for this country.”
Elsewhere in Bangkok, Bank of England chief economist Huw Pill has suggested that the financial markets may be getting carried away by anticipating four increases in UK interest rates over the next year.
Speaking on the sidelines of the IMF’s meeting, Pill said:
“Is it obvious that we will need to move, follow market pricing to four 25 basis-point hikes and so forth? So there, I would be a little bit more sceptical. “I think it is important we get ourselves in the right position. I think we have some work to do there. I think that is something that probably is increasingly obvious now. But is four hikes appropriate over the next year?”
“Is it obvious that we will need to move, follow market pricing to four 25 basis-point hikes and so forth? So there, I would be a little bit more sceptical.
“I think it is important we get ourselves in the right position. I think we have some work to do there. I think that is something that probably is increasingly obvious now. But is four hikes appropriate over the next year?”
Looking at the market pricing this morning, a rate rise in November looks very likely (a 92% chance). The markets then expect three further rate rises by next September.
Bank of England governor Andrew Bailey and IMF managing director Kristalina Georgieva have issued a stark warning about the growing risks of cyber-attacks in the age of AI.
Georgieva cited her childhood growing up in Eastern Europe, when wary citizens didn’t trust the system, so kept their money in a shoebox under the bed.
“What I worry, today, is that unless we figure out how to get ahead of this curve, given the speed, the scale and the cost of fraud growing [going] up, we may end up with lots of people with shoeboxes under their beds.”
Bailey agreed, citing a warning from Anthropic this week that rogue AI agents may ‘self-replicate’ to hijack everyday devices.
“If you try to say what’s at the heart of this debate about AI? For me, it’s about trust in technology and it’s about human control to achieve that trust in technology,” he said, adding:
“I’m going to use a sports metaphor for a moment. I think this technology, you know, is arming the offence, but it can also arm the defence as well.”
And he called for big tech firms to take more responsibility for fraud committed via their platforms. Contrasting their status today with the legal status in the UK of outlets such as newspapers, which are responsible for everything they publish, he said:
“We’ve moved into quite an extreme position of, well, these platforms are open to everybody and there’s no real liability to the provision of the platform to what’s on it. Guess what? Everything’s on it. you know, the good, the bad and the incredibly ugly and and downright criminal and terrible.”
“I don’t go around pointing the finger at people and saying, ‘you are bad’. What I have said is, look, there is responsibility all around. And we need to evolve to a world where everybody understands this responsibility, and everybody is then a part of addressing the problem, because we this cannot be done by by finance alone, given the media that are being used now. We’ve said, ‘look, we’re all in this together.’ The companies that are providing the big tech platforms, the ones we all know, the household names globally, you’ve got to be part of this.”
“I don’t go around pointing the finger at people and saying, ‘you are bad’.
What I have said is, look, there is responsibility all around. And we need to evolve to a world where everybody understands this responsibility, and everybody is then a part of addressing the problem, because we this cannot be done by by finance alone, given the media that are being used now.
We’ve said, ‘look, we’re all in this together.’ The companies that are providing the big tech platforms, the ones we all know, the household names globally, you’ve got to be part of this.”
The pair were speaking on a panel to launch a “Bangkok blueprint for fraud resistance financial services” at the IMF/World Bank annual meetings.
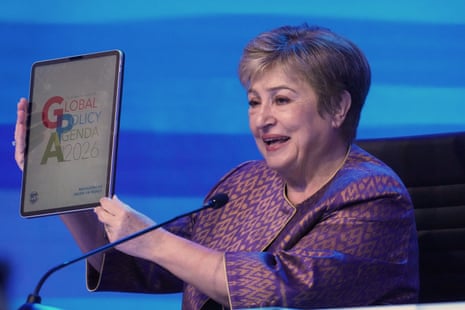
Wednesday morning at the IMF/World Bank annual meetings in Bangkok saw IMF managing director Kristalina Georgieva give her opening press conference, our economics editor Heather Stewart writes.
She enthusiastically reiterated the IMF’s call for major economies - including the US - to implement tougher fiscal policies. “Make urgent repairs to the fiscal house, before the cracks widen,” she said - and later:
“Fundamentals matter. Get your house in order. Otherwise, your people, your businesses will pay a price.”
She highlighted the imbalances between countries with big trade and fiscal surpluses - including China - and those with deep deficits, such as the US.
“Surplus countries need to increase domestic consumption. Deficit countries need to save more, cut debt, cut the deficits over time.”
Georgieva was also asked about fiscal conditions in Europe - including France’s budget predicament; and why the UK’s bond yields remain so high, despite having a plan to cut its deficit - which the IMF has praised this week.
On the UK, she said:
“we need to recognise that it is not just a systemically important, signficant economy, but London is one of the capitals of the world for the finance community. And traditionally we have seen more attention in relative terms in the UK to what the government is doing, what is happening - a bit more sensitivity.”
“I think the UK government knows they need to stay the course: they need to reaffirm this confidence in the direction of travel.”
On France, she insisted she was “positive,” about the government’s prospects of passing a budget that reduces future deficits and might reassure financial markets; but suggested the country’s travails were having knock on effects.
“We are seeing, across the eurozone, an impact in terms of yields edging upwards, even in countries that traditionally never see their yields move.”
Pressure to increase defence spending is another factor pushing up government borrowing – and European countries may need to fund it through spending cuts rather that higher taxes or borrowing, the Fund indicated.
Speaking today in Bangkok, Rodrigo Valdes, head of the IMF’s fiscal affairs department, told reporters:
“I think what countries should do from the macro perspective depends a lot in terms of their initial position. In general, however, the the defence spending will be persistent, so even if you accommodate it temporarily with debt, you have to be prepared at some point to recognise that that debt cannot forever finance this part. And the second issue is that...in general, Europe has really high revenue ratios. So the space for a lot more revenues is not easy: it distorts, at the end of the day. So, the discussion about the social contract behind spending is very, very urgent.”
“I think what countries should do from the macro perspective depends a lot in terms of their initial position. In general, however, the the defence spending will be persistent, so even if you accommodate it temporarily with debt, you have to be prepared at some point to recognise that that debt cannot forever finance this part.
And the second issue is that...in general, Europe has really high revenue ratios. So the space for a lot more revenues is not easy: it distorts, at the end of the day. So, the discussion about the social contract behind spending is very, very urgent.”
Valdes’s colleague Era Dabla-Norris warned:
“Given the fact that many of these spending pressures are going to be persistent, there are going to be difficult trade-offs, and countries are going to have to assess carefully, in communication and dialogue and discussion with the public, in terms of what the priorities are, what needs to come first, and what governments need to spend on.”